A warehouse can be full while the order book remains difficult to serve. In a salt or sodium-product operation, pallets of one grade may sit untouched while customers request a different purity, particle size, or pack format. The apparent asset then consumes cash, storage capacity, and handling time without generating sales.
Slow-moving inventory erodes margins through financing costs, additional handling, quality deterioration, discounts, and potential write-downs. The first corrective step is not a blanket stock reduction: it is separating genuinely recoverable inventory from stock with no credible demand, then adjusting purchasing and production to the specifications customers actually buy.
The margin loss starts before a write-down
Inventory may remain on the balance sheet at its recorded value long after its economic contribution has weakened. Money committed to unsold materials cannot fund faster-selling grades, maintenance, or other operating needs. Borrowed working capital adds financing expense; internally funded inventory still carries an opportunity cost.
Storage creates further costs, but the relevant measure is more than warehouse rent. Extra inspections, damaged-pack replacement, movement between locations, and repeated sampling all consume resources. A crowded warehouse may also slow dispatch of profitable orders or require overflow storage.
For some salt grades, moisture pickup and caking can make material unsuitable for a customer's feeding or dissolution process even when chemical purity remains acceptable. Packaging deterioration may introduce contamination or weaken containment. These effects depend on the material, package, and storage conditions; age alone does not prove that a batch has failed.
Finally, recovering the original production cost becomes harder when customer requirements change. A sale may require repacking, requalification, or a discount. Those recovery costs reduce the remaining contribution, even if the stock eventually ships.
Calculate the cost of waiting, not just the stock value
A useful review compares two measures: the inventory's recorded value and its expected net recovery. Expected recovery should reflect a realistic selling price, less the incremental costs necessary to make and complete the sale. Avoid assuming that the latest invoice price applies to an aging batch with different packaging or specifications.
For management decisions, estimate the cost of holding stock over the review period as financing cost plus incremental storage, handling, testing, and expected deterioration or discount losses. Keep accounting treatment separate: some of these costs affect gross margin, while others appear in operating or financing expenses. All can reduce business profitability.
Do not count the same loss twice. For example, if an expected selling price already includes a quality-related discount, adding that discount again as a separate recovery cost overstates the exposure. Likewise, allocated warehouse overhead is not automatically a cash saving when inventory leaves.
Find the specification mismatch behind the aging total
A total labeled “sodium products” is too broad for a useful decision. Review stock by product, grade, batch, particle characteristics, packaging, and customer approval status. Two batches with the same general chemical description may not be interchangeable in a buyer's process.
The inventory record should connect each batch to its production or receipt date, last movement, quality status, storage conditions, and demand history. Distinguish shipments from internal transfers: moving pallets between warehouses does not demonstrate market demand.
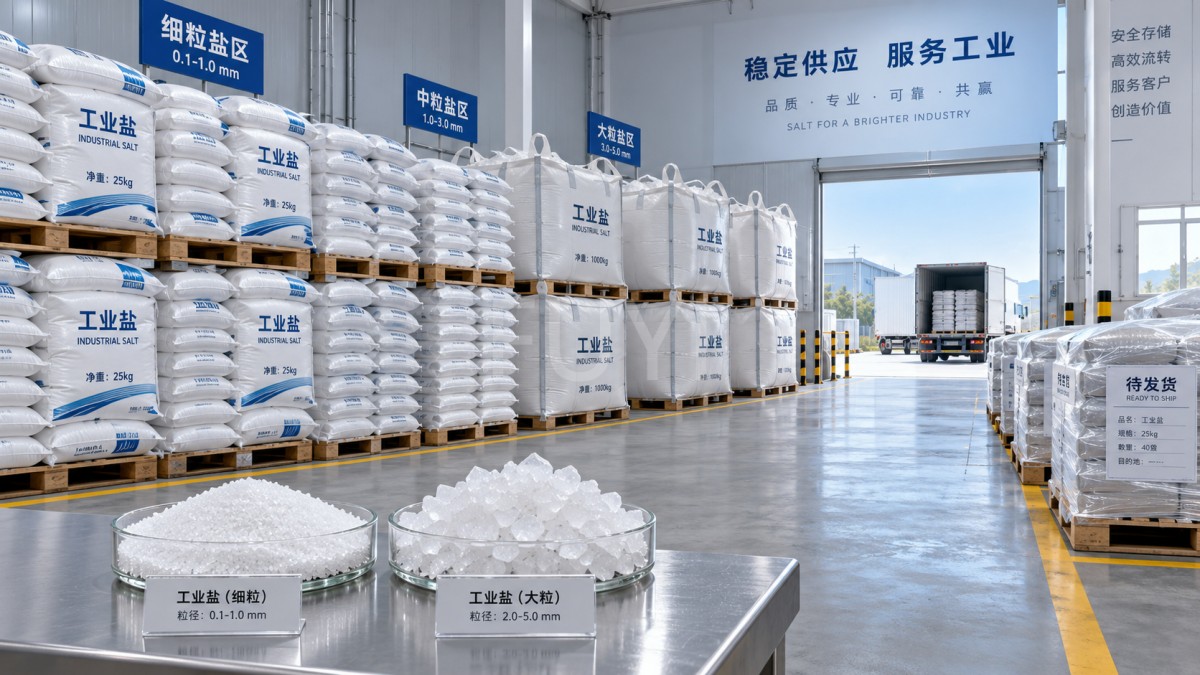
Then compare available stock with demand that can actually consume it. Firm orders are stronger evidence than enquiries, and an approved specification is stronger than a possible alternative application. Include material already on order or scheduled for production; otherwise, a purchasing decision can recreate the surplus before existing stock is reduced.
There is no universal age threshold for all chemicals. A stable grade with predictable seasonal demand may reasonably move slowly. A moisture-sensitive material, short qualification window, or discontinued customer specification needs earlier attention. Aging bands should trigger investigation according to product risk and replenishment lead time, not automatically trigger disposal.
Procurement savings can create a more expensive stock problem
Large purchase quantities and long production campaigns often lower the apparent unit cost. The saving becomes questionable when the extra volume exceeds credible consumption. Longer runs may reduce changeover costs while leaving an unpopular grade in storage and delaying production of a grade customers need.
Compare purchasing or campaign options using total relevant cost: acquisition or production cost, freight, changeover costs, carrying cost, and likely recovery losses. A smaller delivery can be economically preferable even at a higher unit price, provided continuity of supply remains acceptable.
This discipline also applies to organic intermediates held alongside salt products. The listing for Ethanol chloride states purity of at least 99%, molecular formula C2H3ClO, molecular weight 78.5, and CAS No. 75-36-5, with 200 kg galvanized iron drums or customer-required packaging. It describes use as an intermediate in organic synthesis, pharmaceutical chemistry, and pesticide chemistry.
Before procurement, resolve the identity discrepancy: CAS No. 75-36-5 identifies acetyl chloride, so the listing name should not be used alone to approve a purchase. Confirm the chemical identity, safety data sheet, and package compatibility. A listed pack format is not evidence that it suits every storage duration or condition. Unresolved documentation can leave inventory unusable for an intended order despite an acceptable stated purity.
Choose a recovery route batch by batch
Start with quality and market eligibility rather than price reduction. A discount cannot make an unsuitable batch acceptable, and an internal decision to reclassify material does not replace customer approval.
- Sell against confirmed demand. Match batch results and packaging to the customer's current specification, then verify that the proposed price covers remaining fulfillment costs.
- Repack or rework only with a defined destination. Confirm technical feasibility, approved procedures, expected yield, and acceptance criteria before spending more money. Reworking stock without demand merely changes the form of the surplus.
- Consider an alternative application. Obtain approval for the actual specification and maintain accurate labeling and traceability. Do not represent an off-spec batch as meeting its original grade.
- Use an approved disposal route where recovery is not viable. Compare the expected proceeds with testing, processing, selling, and holding costs. Environmental and safety requirements remain applicable regardless of the stock's commercial value.
Finance should assess whether the carrying value remains supportable under the applicable accounting policy. Write-downs recognize a loss; they do not release warehouse space or cash. Physical disposition and financial valuation therefore need separate owners and deadlines.
Make replenishment respond to usable stock
After identifying excess, change the decision that created it. Purchasing and production planning should see usable inventory, open orders, scheduled output, and specification-level demand together. Stock awaiting qualification should be visible but not treated as immediately available for every customer.
Review minimum order quantities and campaign sizes when demand changes. Preserve safety stock where supply interruption would be costly, but set it from lead-time uncertainty and consumption variability rather than from an unsupported forecast. Where suitable, align delivery schedules with consumption instead of accepting the full purchase quantity at once.
Track aging value alongside inventory turns, quality holds, and sales recovered after incremental costs. Assign each slow-moving batch an action, accountable owner, and next review date. A proposed production run or purchase should be challenged whenever equivalent usable stock already exceeds credible demand—even when the new unit cost looks attractive.
Leave A Message
If you are interested in our products and want to know more details, please leave a message here, we will reply you as soon as we can.